Research /Research
Who's Actually Winning New York Cannabis
713 brands are fighting over one Manhattan market. Ten of them take a third of it — and the top three have almost nothing in common.
Watch the story

Seven months into 2026, 713 cannabis brands recorded sales in Manhattan's licensed dispensaries. Together they moved 4.82 million units worth an estimated $167.7 million, at an average of $34.78 an item.
That sounds like a crowded, fragmented market — and at the bottom it is. Only 40 brands cleared $1 million. But at the top it concentrates fast: the ten biggest brands take 30.7% of every dollar.
What makes this list worth studying isn't who's on it. It's that the brands at the top got there in completely different ways.
The Top 10 Brands in Manhattan
| # | Brand | Est. retail | Units | Avg price | Share of $ |
|---|---|---|---|---|---|
| 1 | ayrloom | $7.69M | 297,703 | $25.83 | 4.59% |
| 2 | Ruby Farms | $6.60M | 175,584 | $37.58 | 3.93% |
| 3 | Fernway | $6.27M | 99,697 | $62.86 | 3.74% |
| 4 | Rythm (GTI) | $5.32M | 87,024 | $61.15 | 3.17% |
| 5 | Camino (Kiva) | $4.91M | 162,471 | $30.21 | 2.93% |
| 6 | MFNY | $4.76M | 129,570 | $36.72 | 2.84% |
| 7 | Off Hours | $4.47M | 144,440 | $30.94 | 2.67% |
| 8 | Florist Farms | $3.92M | 115,223 | $34.04 | 2.34% |
| 9 | Dank. by definition. | $3.78M | 108,989 | $34.65 | 2.25% |
| 10 | Jaunty | $3.74M | 84,292 | $44.38 | 2.23% |
Look at the price column. The #1 brand sells at $25.83. The #3 brand sells at $62.86 — two and a half times more — and they finish within $1.4M of each other. That gap is the whole story of this market.
Three ways to win
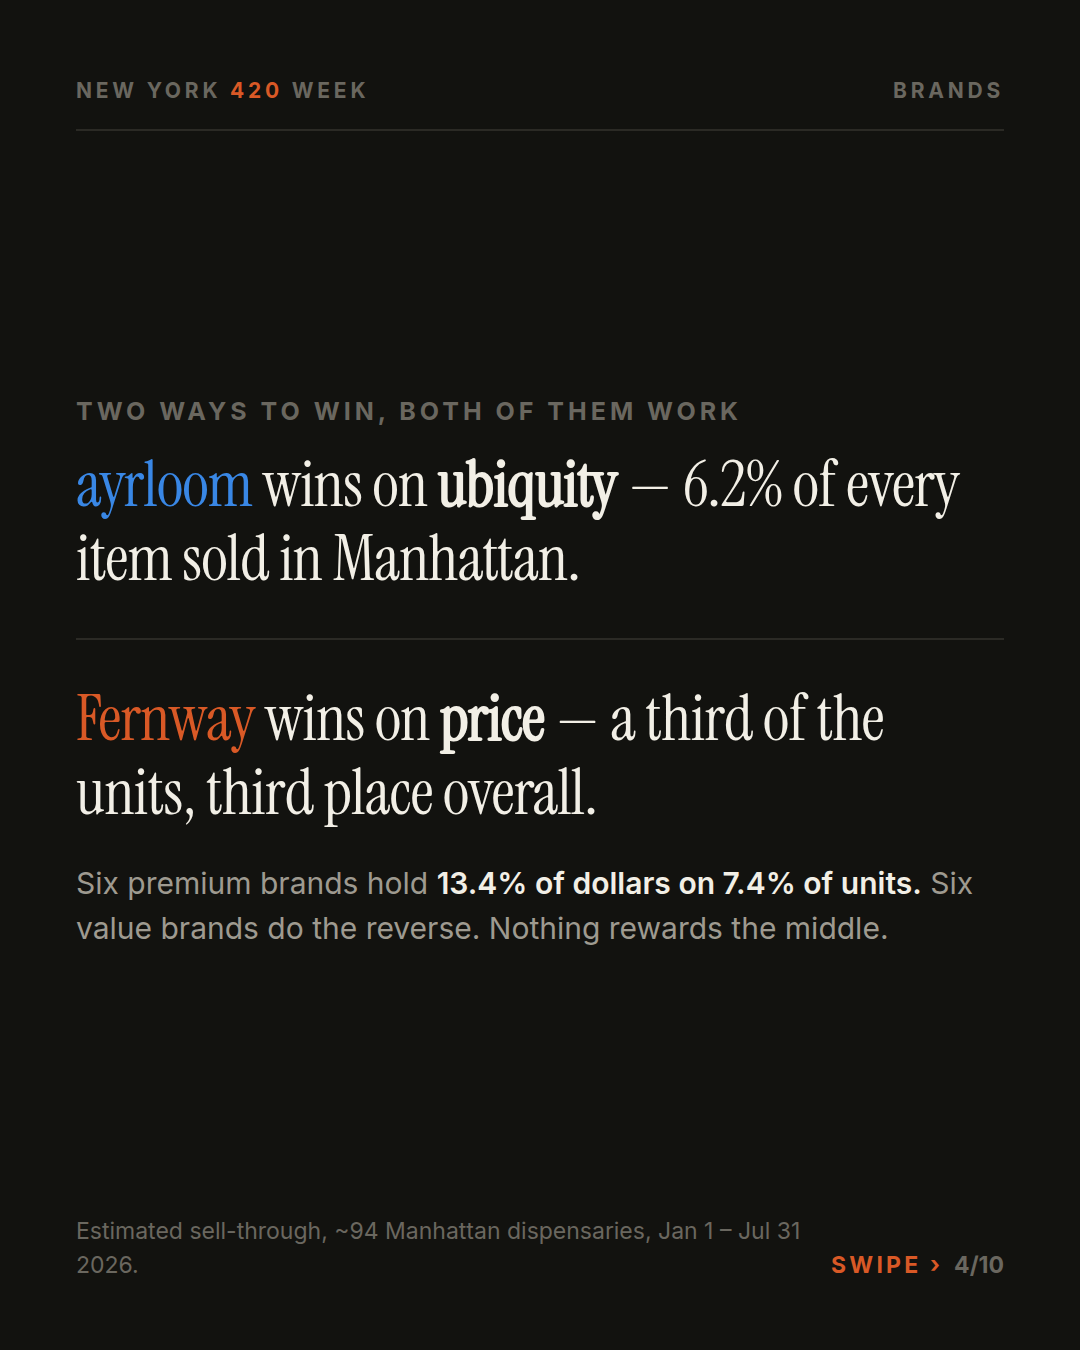
ayrloom wins on ubiquity. It moved 297,703 units — 6.2% of every single item sold in Manhattan this year, more than any other brand by a wide margin. At $25.83 a unit it's the cheap, high-frequency purchase: the beverage in the fridge, the gummy in the bag. Volume is the entire strategy, and it works.
Fernway wins on price. It sold roughly a third of ayrloom's units — 99,697 — and converted them into $6.27M, landing third overall. At $62.86 a unit, Fernway doesn't need footfall; it needs the customer who already knows what they want. It is the clearest proof in this dataset that premium is a viable path to the top of a market, not a niche beside it.
That divide holds across the whole leaderboard. The six premium brands priced $58–78 (Fernway, Rythm, Pax, Rove, Jetty, Heavy Hitters) hold 13.4% of all dollars on just 7.4% of units. The six value brands under $28 (ayrloom, Wyld, Nanticoke, Grön, Revert, Heady Tree) do the reverse: 14.9% of units for 10.4% of dollars. Two completely different businesses, both profitable at scale.
Ruby Farms wins on momentum — and it's the most interesting brand in New York right now.
The takeover
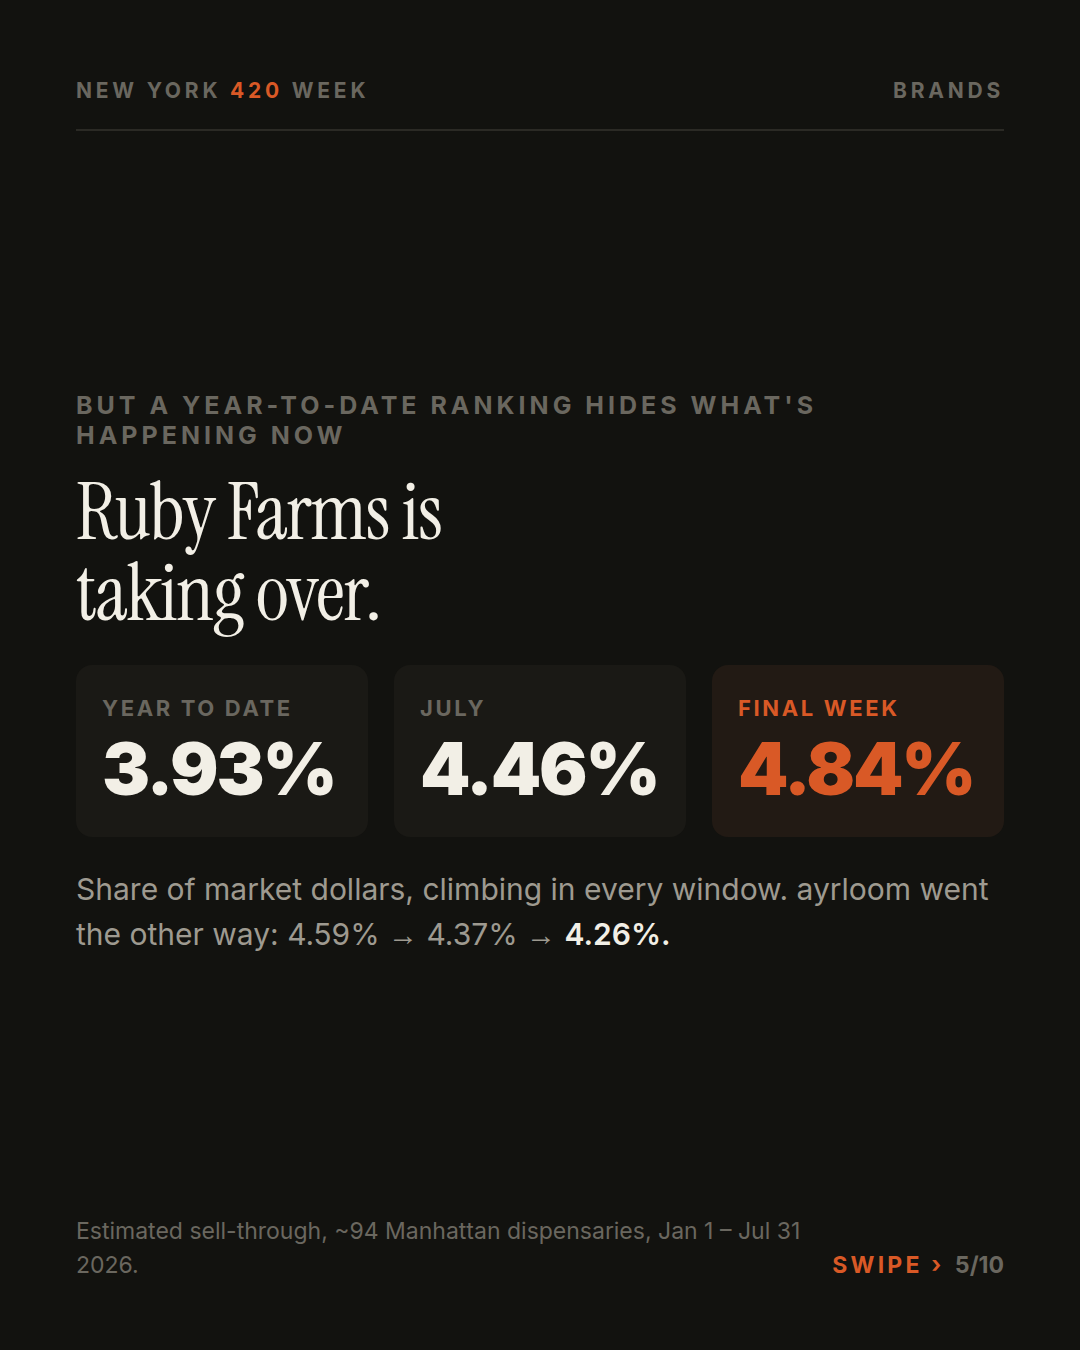
Ruby Farms finished the seven months in second place. But a year-to-date ranking is an average, and averages hide what's happening now. Tracking its share of market dollars across progressively more recent windows:
- Year to date (Jan–Jul): 3.93%
- July alone: 4.46%
- Final week (Jul 24–30): 4.84%
It climbed in every single window. Meanwhile ayrloom went the other way — 4.59% → 4.37% → 4.26%.
In July, Ruby Farms out-earned ayrloom outright: $1,098,544 versus $1,077,107. The #1 brand of the year lost the month to the brand in second place, and by the last week of July the gap had widened. If the trend held into August, the leaderboard has a new name at the top.
Where share is actually moving
Comparing each brand's July share against its own year-to-date baseline shows who is accelerating and who is coasting on earlier months:
Gaining ground: Ruby Farms (+0.52 points), Stiiizy (+0.42), Jetty (+0.40), Heavy Hitters (+0.28), Anthem (+0.27), Fernway (+0.22). Five of those six are premium vape or concentrate brands — the format winning the summer.
Losing ground: Dank. by definition. (−0.54, and still falling — down to 1.37% in the final week), Rythm (−0.36), MFNY (−0.32), Rove (−0.30), Off Hours (−0.24), ayrloom (−0.22).
Notice that four of the six decliners are top-10 brands. In a market growing this fast, standing still is a loss.
The houses behind the brands
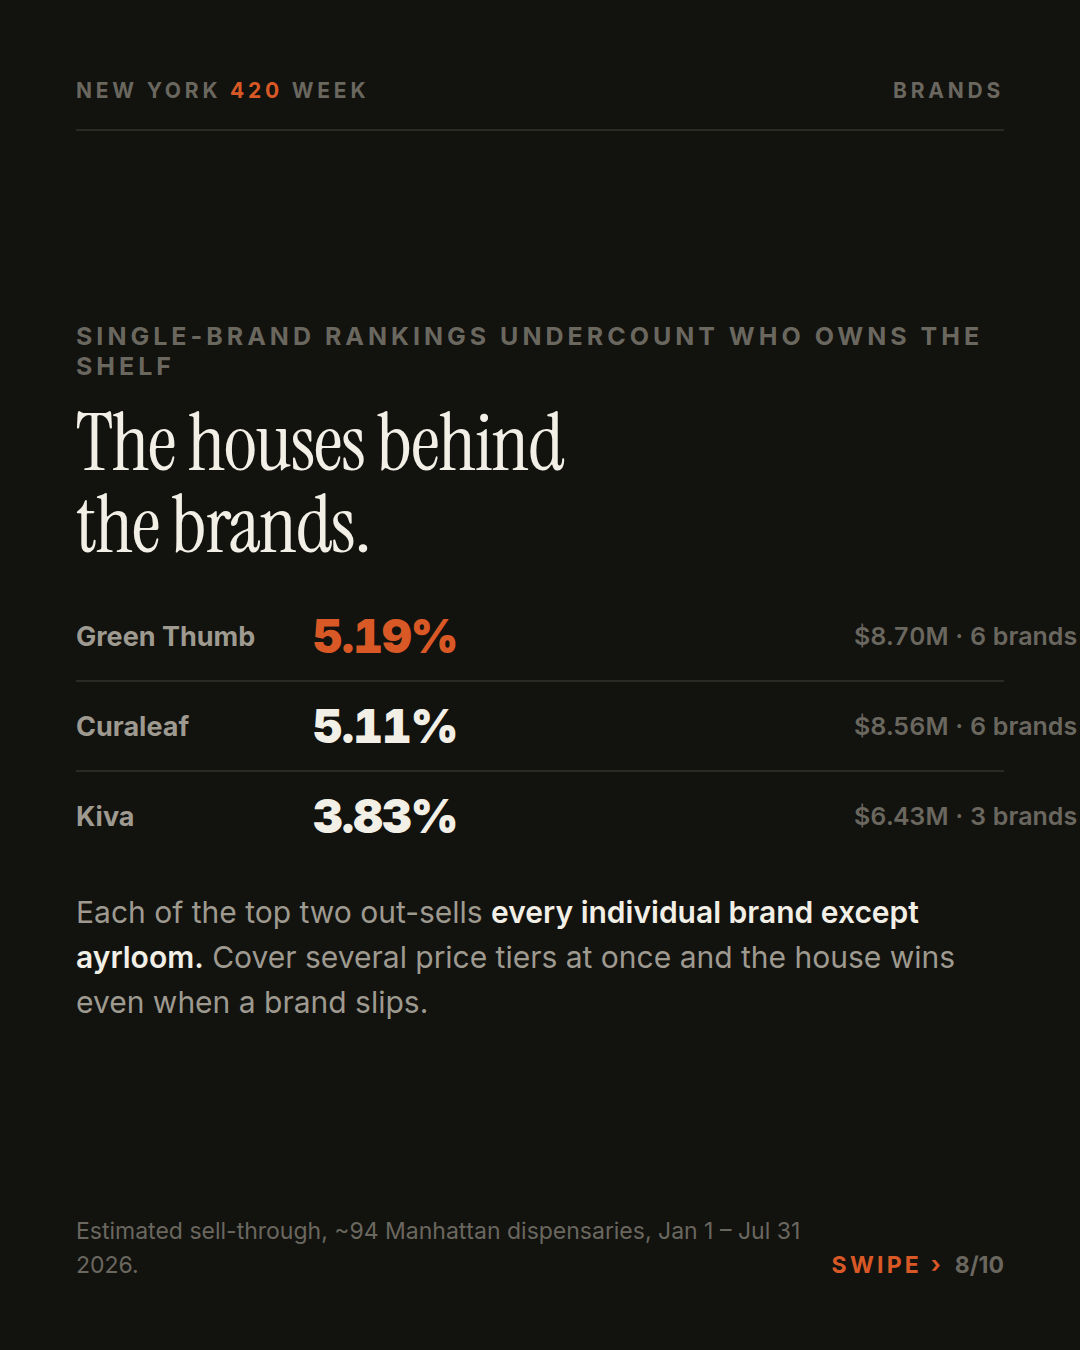
Single-brand rankings undercount who actually controls shelf space. Rolled up to parent companies:
- Green Thumb Industries (Rythm, Dogwalkers, incredibles, Good Green, &Shine, Beboe) — $8.70M, 5.19% of all dollars
- Curaleaf (Anthem, Grassroots, Select, Find, B Noble, JAMS) — $8.56M, 5.11%
- Kiva (Camino, Lost Farm, Kiva) — $6.43M, 3.83%
Each of the top two out-sells every individual brand in New York except ayrloom. The multi-brand portfolio is a strategy in itself: cover several price tiers and formats at once, and the house wins even when any one brand slips.
One state, several markets
Manhattan is not New York. Statewide through September 6, licensed dispensaries did $1.167 billion across 630 stores and roughly 1,150 brands — a far flatter field, where the single largest brand holds just 4.2% of brand-attributed dollars.
And regional taste diverges sharply. Comparing each region's brand mix against the state, Manhattan over-indexes on low-dose edibles and hardware — Bloom 3.06×, Camino 2.07×, Pax 1.89×, Wyld 1.65×. Long Island over-indexes on value and volume brands — The Plug Pack 4.00×, Bodega Boyz 3.13×, Left Coast 2.40×.
The starkest example: The Plug Pack does 4.00× its expected share on Long Island and 0.11× in Manhattan. Same state, same legal market, effectively two different customers. Manhattan also runs a shorter shelf — its top 50 brands take 68.6% of dollars versus 64.4% statewide.
One more piece of statewide context that frames everything above: the market grew +31.7% from January to August, and that growth was entirely volume. Average price fell 6.5% ($36.85 to $34.46). More people are buying more units, and paying less per unit. Brands winning on volume are swimming with that current; brands winning on price are swimming against it — which makes Fernway's and Jetty's gains more impressive, not less.
What to do with this
If you're shopping: the price spread on this list is the real finding. Brands 1 and 3 are separated by $37 an item. Know which trade you're making.
If you're a brand: pick a lane and commit. The data shows volume and premium both reaching the top ten; nothing here rewards the undifferentiated middle. And watch the momentum column rather than the year-to-date ranking — it's six months more current.
If you're a retailer: Ruby Farms, Stiiizy, Jetty and Heavy Hitters were taking share as of late July, and four of the ten biggest brands were giving it back. A shelf built on last year's leaderboard is already behind.
Figures are estimated retail sell-through from brand-level analytics covering roughly 94 licensed Manhattan dispensaries across five overlapping windows, January 1 – July 31, 2026. Momentum is a window's share of market dollars minus its year-to-date share, so a positive figure means the brand beat its own seven-month average. Statewide and regional figures come from separate extracts and are reported on their own basis — the two are never summed, and the named brand ranking above is the Manhattan market only. All values are the provider's estimates, not audited sales.
Words by Greg Silverstein · @newyork420week · @sourcatjack